The short answer: We expect non-resident digital services providers to collect Brazil’s CBS and IBS on both B2B and B2C sales from January 1, 2027. That date is not confirmed, and the implementing rules are not final. Our team is tracking every update and will support registration and filing in Brazil if non-residents are in scope.
What we expect from Brazil's new tax reform
Brazil’s indirect tax reform fundamentally overhauls the country’s complex, fragmented tax system by introducing a dual VAT framework comprising the federal level Goods and Services Contribution (CBS) and the state and municipal level Goods and Services Tax (IBS). This transition is scheduled to take place gradually between 2026 and 2033.
Under the new framework, CBS will replace PIS and COFINS, while IBS will replace state-level ICMS and municipal ISS. The existing IPI will largely be phased out, with the Selective Tax (IS) introduced to apply to certain goods and services. The reform aims to simplify tax administration, improve transparency, and create a more harmonized indirect tax system across Brazil.
Although the existing and new indirect tax regimes will coexist during the transitional period between 2026 and 2033, this does not mean that both regimes will apply to all taxpayers. For non-resident SaaS and other foreign digital service providers, the existing domestic tax regime does not apply in the same manner as it does to resident businesses. The transition to CBS and IBS should be viewed as new rules applicable to non-resident suppliers, rather than as a gradual transition away from legacy tax obligations.
While detailed implementing regulations and guidance for non-resident businesses have not yet been published, several key developments are expected to affect foreign digital service providers operating in Brazil.
1. New tax collection obligations for non-resident digital service providers
From January 1, 2027 (subject to confirmation), non-resident digital service providers are expected to become responsible for collecting CBS and IBS on both business-to-business (B2B) and business-to-consumer (B2C) transactions.
This represents a significant change for foreign businesses supplying digital services to Brazilian customers, potentially bringing new tax registration, collection, and reporting obligations.
Anrok is preparing to support non-resident businesses with the associated Brazilian tax registration, tax determination, calculation, and filing requirements, should these obligations apply as anticipated.
2. Introduction of a split payment mechanism
Brazil’s tax reform also introduces a split payment mechanism, whereby financial institutions will automatically withhold the CBS and IBS amounts from transaction payments and remit them directly to the tax authorities.
However, implementation may take longer than initially anticipated. Recent discussions suggest that the introduction of the split payment mechanism could be deferred until 2028, with selected companies already reporting challenges during early implementation efforts.
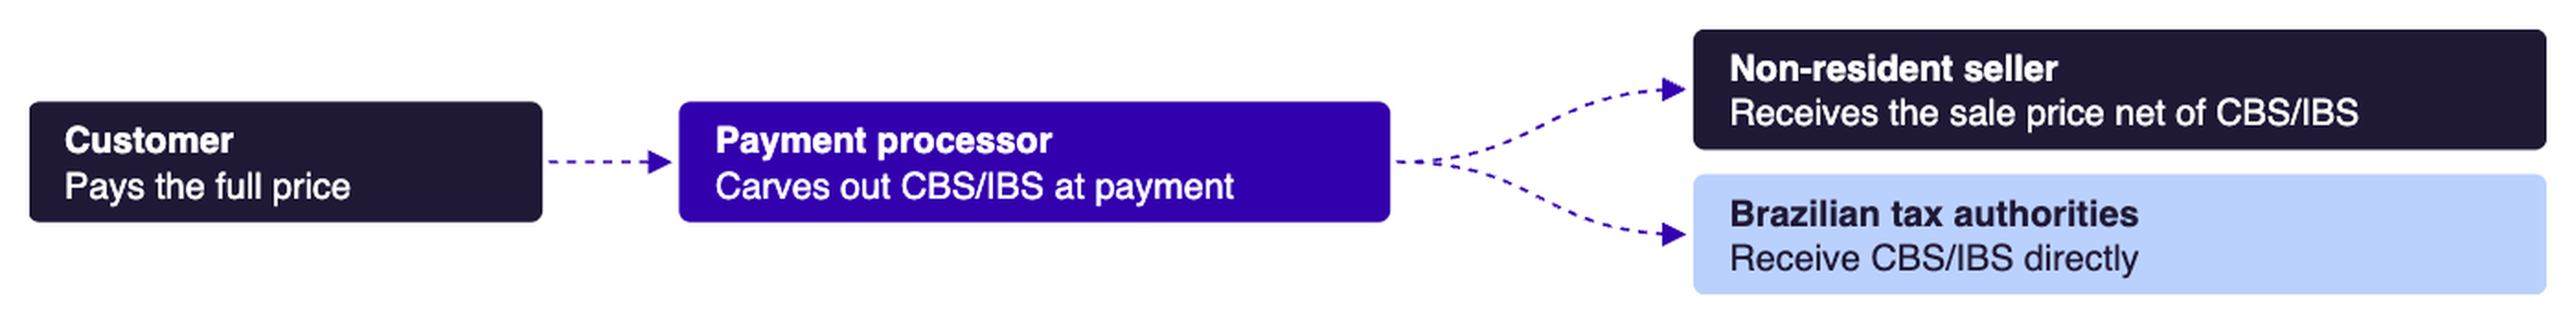
The timing and practical application of the mechanism, particularly for non-resident businesses, remain subject to further clarification. Anrok is closely monitoring developments and, in the meantime, is focused on supporting non-resident businesses with CBS and IBS tax determination and calculation.
3. Potential e-invoicing requirements for non-resident businesses
The application of Brazil’s e-invoicing framework to non-resident businesses remains an area of uncertainty. In particular, it has yet to be confirmed whether foreign digital service providers will be required to issue Brazilian electronic invoices (NF-e or NFE-s).
Further regulatory guidance is needed to clarify the applicable requirements, including the invoicing processes and technical obligations for non-resident providers.
Anrok intends to support applicable e-invoicing requirements should they be introduced, drawing on its experience supporting businesses with similar obligations in markets such as Taiwan, Mexico, and the UAE for non-resident digital service providers.
4. Potential implementation delays and transitional relief
Several factors introduce uncertainty around Brazil’s anticipated January 2027 implementation timeline. Brazil has recently held an election, and the timing of outstanding regulatory decisions may be affected by the transition. With relatively little time remaining before the expected effective date, detailed implementing regulations and guidance for non-resident businesses have yet to be finalised, leaving businesses with limited time to understand and prepare for their new obligations.
There is also precedent for implementation delays and transitional relief in other jurisdictions, particularly for new e-invoicing regimes and tax requirements affecting non-resident businesses. Given these factors, there remains a possibility that Brazil could adjust certain implementation deadlines or introduce transitional relief, including a grace period for non-resident businesses.
However, no formal postponement or grace period has been confirmed. Businesses should therefore continue preparing on the basis of the currently anticipated timelines while monitoring further announcements from the Brazilian tax authorities.
How Anrok is preparing
Anrok is closely monitoring developments in Brazil and the release of further regulatory guidance. We are preparing to support non-resident businesses with the new CBS/IBS requirements, including tax registration, determination, calculation, and filing, should these obligations apply. We also intend to support any applicable e-invoicing requirements for non-resident businesses.
There is no action required from you at this stage. Once the registration process and compliance requirements are confirmed, we will communicate the relevant timelines and provide clear guidance on any steps you need to take. Given the potentially short lead time between the release of final guidance and the effective date, we are actively monitoring developments to help ensure you are prepared.
If you have any questions or would like to discuss how the reform may affect your business, please book some time with our team.